An entrepreneur can have an interesting product, a promising market, and a business idea that attracts attention, yet still struggle to turn that opportunity into a sustainable company. The difficulty often becomes clear when the initial excitement meets the practical requirements of running a business. Product development needs money, employees expect salaries, marketing requires investment,
An entrepreneur can have an interesting product, a promising market, and a business idea that attracts attention, yet still struggle to turn that opportunity into a sustainable company. The difficulty often becomes clear when the initial excitement meets the practical requirements of running a business. Product development needs money, employees expect salaries, marketing requires investment, suppliers must be paid, and customers may take longer than expected to generate consistent revenue. Without a clear understanding of these financial responsibilities, even a promising startup can face avoidable problems.
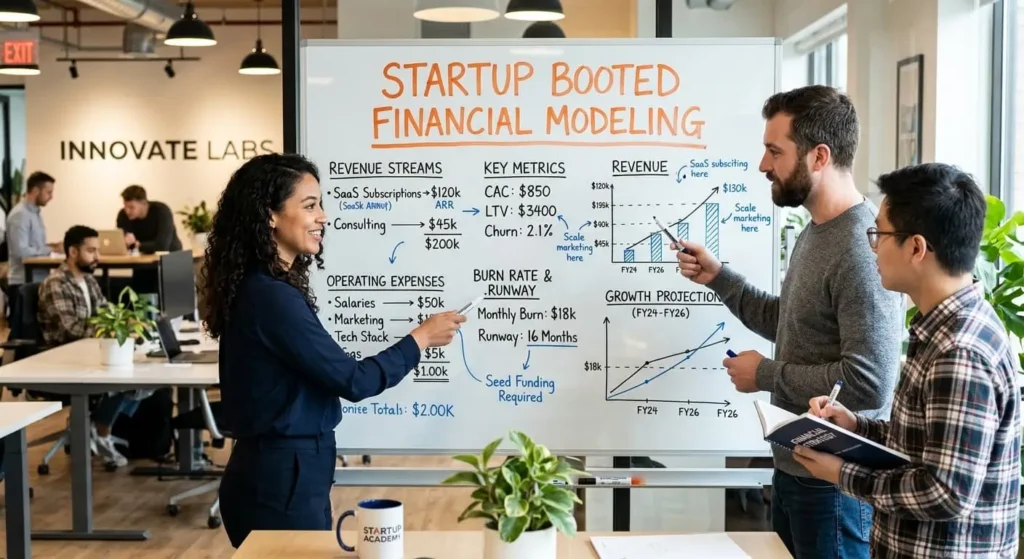
This is where Startup Booted Financial Modeling becomes an important concept for entrepreneurs. It represents the process of building a structured financial picture of a startup, beginning with its basic business assumptions and developing them into revenue forecasts, expense estimates, cash flow projections, funding requirements, and profitability calculations. Instead of relying entirely on intuition, founders can use a financial model to examine how different business decisions may affect the company’s financial position.
Startup financial modeling is not simply about predicting how much money a business might earn. It is about understanding the relationship between what a company plans to sell, what it must spend, when it receives payments, and how much capital it needs to continue operating. A useful model also helps founders identify potential financial difficulties before they become serious problems.
The term Startup Booted Financial Modeling is best understood here as an educational topic rather than the name of a verified company, software product, or established financial platform. Its practical value lies in the financial planning process itself. By understanding the numbers behind a business idea, entrepreneurs can make more informed decisions about launching, managing, financing, and expanding their startups.
Quick Business Concept Profile
| Fact | Details |
|---|---|
| Concept Name | Startup Booted Financial Modeling |
| Subject Area | Startup Finance and Business Planning |
| Main Focus | Financial modeling for early-stage businesses |
| Primary Users | Startup founders and entrepreneurs |
| Key Components | Revenue, expenses, cash flow, and projections |
| Main Objective | Support informed financial decisions |
| Business Applications | Budgeting, forecasting, and planning |
| Financial Planning Stage | Early-stage and growth-stage businesses |
| Important Financial Metrics | Revenue, burn rate, runway, and profitability |
| Common Tools | Spreadsheets and financial modeling software |
| Long-Term Relevance | Financial monitoring and strategic planning |
Understanding Startup Booted Financial Modeling
Startup Booted Financial Modeling can be understood as a structured approach to estimating the financial requirements and possible outcomes of a new business. The word “booted” can be interpreted in the context of bootstrapping, where founders begin with limited resources and attempt to build operations through personal investment, early sales, or internally generated cash. However, financial modeling is equally relevant to startups seeking outside investment. The central idea is to understand the financial mechanics of the business before making commitments that may be difficult to reverse.
A financial model translates a business plan into numerical relationships. It connects expected sales with pricing, customer acquisition, operating expenses, payroll, investment requirements, and cash availability. These elements work together to show how a startup might perform under different circumstances.
For example, an entrepreneur planning to launch an online subscription service may estimate the number of customers required to cover monthly expenses. The model could include subscription prices, expected customer growth, payment processing costs, software expenses, advertising, and employee salaries. By changing one assumption at a time, the founder can examine how the company’s financial position might change.
This approach makes financial planning more practical. Instead of saying that a business needs more customers, a founder can estimate how many paying customers are necessary to cover operating costs. Instead of assuming that a marketing campaign will be successful, the founder can calculate how different customer acquisition costs affect the business.
Financial Modeling Versus a Traditional Business Plan
A traditional business plan explains the company’s purpose, market opportunity, products, competition, strategy, and operational structure. It provides the broader explanation of how the business intends to operate.
A financial model concentrates on the numerical consequences of those plans. It estimates the amount of revenue the business might generate, the costs required to support operations, and the capital needed to reach its objectives.
The two documents complement each other. A business plan may describe an intention to hire a development team, while the financial model estimates recruitment costs, monthly salaries, equipment expenses, and the timing of those payments. Similarly, a business plan may identify a target customer segment, while the model translates expected customer acquisition into projected sales.
A financial model should therefore support the business plan rather than operate as an unrelated spreadsheet. Its assumptions should reflect the company’s actual strategy, and its calculations should make that strategy financially understandable.
Why the Bootstrapping Perspective Matters
Bootstrapped businesses often operate under tighter financial constraints than companies with substantial external funding. Their founders may need to prioritize essential expenses, delay unnecessary hiring, negotiate supplier terms, and use early revenue to support additional development.
This makes financial modeling particularly valuable. A founder with limited capital cannot afford to overlook recurring expenses or assume that customer payments will arrive immediately. Even a small forecasting error can create pressure when the company has little financial flexibility.
A carefully prepared model helps founders distinguish between expenses that are essential for launching the business and investments that can wait until revenue becomes more predictable.
Why Financial Models Matter Before a Startup Begins
Starting a business involves making decisions with incomplete information. Entrepreneurs may understand the problem they want to solve, but they rarely know exactly how many customers will purchase their product, how quickly sales will develop, or how much money operations will consume. Financial modeling provides a framework for examining these uncertainties before they turn into expensive commitments.
A startup financial model is especially useful during the early planning stage because it encourages founders to test whether their business idea is financially practical. It does not guarantee success, but it can reveal weaknesses in the original plan and help entrepreneurs identify what must change.
Testing Whether a Business Idea Is Financially Practical
An idea may attract potential customers without generating enough revenue to support a company. This can happen when the product is priced too low, customer acquisition is expensive, production costs are underestimated, or the business requires more employees than initially expected.
Financial modeling brings these factors together. Suppose an entrepreneur plans to sell a digital product for a monthly subscription. The founder can estimate how many subscribers are required to cover software costs, marketing expenses, customer support, and other overheads.
If the model shows that the business needs an unrealistic number of subscribers to reach break-even, the founder has an opportunity to reconsider the pricing strategy or cost structure before investing heavily.
The same process can be applied to physical products, consulting businesses, mobile applications, marketplaces, and service-based startups. The specific calculations differ, but the underlying question remains the same: can the business generate enough financial resources to support its operations?
Making Better Decisions About Limited Capital
Early-stage businesses usually have competing financial priorities. Founders may need to purchase equipment, develop a product, pay for licenses, hire employees, establish a website, and promote their offering. Spending too much on one area can leave insufficient money for essential activities elsewhere.
Startup budgeting helps organize these commitments. A financial model can show when particular expenses are expected to occur and how they may affect the remaining cash balance.
This is particularly important for bootstrapped entrepreneurs because their ability to recover from financial mistakes may be limited. A model that identifies upcoming cash requirements can help founders delay optional spending and protect money needed for essential operations.
Preparing for Financial Conversations
Financial models also help entrepreneurs communicate their plans to investors, lenders, business partners, and other stakeholders. A founder who understands projected revenue, expenses, cash requirements, and business assumptions can explain how the company expects to operate.
Investors may want to understand the logic behind a startup’s growth expectations. They may ask how the company calculates its addressable customer base, what it expects to spend acquiring customers, how long available capital will last, and when profitability might become possible.
A financial model gives founders a structured way to answer these questions. It also makes it easier to identify areas where additional research or stronger evidence is necessary.
Creating a Reference Point for Measuring Performance
A financial forecast is useful even when actual results differ from expectations. Founders can compare projected revenue with actual sales, planned expenses with recorded costs, and expected cash flow with the company’s real financial position.
These comparisons help identify the reasons behind performance differences. Perhaps sales are lower because customer acquisition is taking longer. Perhaps expenses are higher because suppliers have increased their prices. Perhaps the company is receiving payments later than expected.
Without an initial financial model, founders may struggle to identify whether the business is performing according to plan. With one, they have a reference point for reviewing decisions and adjusting their strategy.
The Building Blocks of an Effective Startup Financial Model
An effective financial model is built from connected financial statements, assumptions, and supporting calculations. Each part answers a different question, but the sections should work together to produce a consistent picture of the business.
Most early-stage models begin with a small number of important inputs and become more detailed as the business develops. Adding unnecessary complexity at the beginning can make the model harder to maintain without improving the quality of decisions.
1. Revenue Assumptions
Revenue assumptions describe how the startup expects to earn money. These assumptions may include selling prices, expected customer numbers, transaction volumes, subscriptions, service contracts, or other sources of income.
A business with multiple products may require separate calculations for each product because their prices, sales volumes, and profit margins can differ.
For a subscription business, revenue may depend on the number of active subscribers, the average monthly subscription price, new customer additions, and cancellations. For a retail business, the model may focus on units sold, average selling price, and repeat purchases.
The important point is that projected revenue should come from understandable business drivers rather than arbitrary growth percentages.
2. Operating Expenses
Operating expenses represent the costs required to keep the business functioning. These may include payroll, office expenses, marketing, software subscriptions, professional services, utilities, and administrative costs.
Some expenses remain relatively stable over a period, while others increase with sales or production. A financial model should recognize these differences because they influence profitability and cash requirements.
3. Initial Startup Costs
Initial costs are expenses associated with preparing the business for operation. They can include product development, equipment, legal registration, branding, initial inventory, website development, and other launch-related requirements.
Not every initial cost is an ongoing expense. Some purchases may be treated as assets and depreciated or amortized according to the applicable accounting treatment. Founders should avoid mixing all startup expenditures into one recurring monthly expense figure.
4. Cash Flow Projections
Cash flow projections estimate when money enters and leaves the business. They are essential because sales and available cash are not always the same thing.
A startup may record revenue from a customer but receive payment several weeks later. Meanwhile, salaries, rent, suppliers, and other obligations may need to be paid immediately.
5. Profit and Loss Forecast
A projected profit and loss statement estimates the business’s financial performance over a defined period. It generally includes revenue, direct costs, operating expenses, and other relevant income or expenses.
This statement helps founders understand whether the company may generate a profit, but it should be interpreted alongside cash flow and the balance sheet.
6. Balance Sheet Forecast
The balance sheet presents the company’s financial position at a particular point in time. It includes assets, liabilities, and equity.
For a startup, important items may include cash, equipment, inventory, accounts receivable, accounts payable, loans, and contributed capital. Including a projected balance sheet helps ensure that the financial model remains connected to the company’s underlying financial position.
7. Financial Assumptions and Supporting Calculations
Every projection depends on assumptions. These may involve pricing, sales growth, employee numbers, supplier costs, customer retention, payment delays, and marketing efficiency.
Assumptions should be documented separately from calculated results. This makes the model easier to review and update when new information becomes available.
Revenue Forecasting: Turning Business Assumptions Into Numbers
Revenue forecasting is one of the most important parts of startup financial modeling because it estimates how the business expects to generate income. However, revenue projections are also among the easiest parts of a model to make overly optimistic.
A founder may believe that a product will attract thousands of customers, but the financial model needs to explain how those customers will discover the product, why they will purchase it, and how much they are expected to spend.
Understanding the Main Revenue Drivers
The appropriate revenue calculation depends on the business model.
For a product-based startup, a basic calculation is:
\[ \text{Revenue}=\text{Units Sold}\times\text{Selling Price} \]
For a subscription company, a simplified monthly revenue calculation is:
\[ \text{Monthly Revenue}=\text{Active Subscribers}\times\text{Monthly Price} \]
For a service business, revenue may depend on the number of projects completed and the average fee charged per project.
A marketplace may generate revenue through commissions, transaction fees, subscriptions, or a combination of these sources. Its model should distinguish between the total value of transactions processed and the revenue actually retained by the marketplace.
A Hypothetical Subscription Business Example
Consider a hypothetical startup offering a digital service for $20 per month. Its founder expects to acquire 100 paying subscribers during an initial period.
The simplified monthly recurring revenue calculation would be:
\[ 100\times \$20=\$2,000 \]
This figure represents projected monthly subscription revenue under the stated assumptions. It does not automatically represent profit or available cash.
The founder would still need to account for payment processing charges, hosting, customer support, marketing, salaries, taxes, refunds, and subscription cancellations.
If the business loses subscribers every month, its revenue forecast must also account for customer churn. If it acquires new customers, the model should include those additions separately.
This approach creates a more useful forecast because it shows where revenue comes from and which assumptions have the greatest influence on the result.
Customer Acquisition and Conversion Rates
Startups often rely on marketing activities to attract potential customers. However, the number of people who see an advertisement is different from the number who visit a website, and the number who visit a website is different from the number who purchase a product.
A revenue model can reflect these stages.
For example, suppose a hypothetical business receives 5,000 website visits during a month and converts 2% of those visitors into paying customers. That produces 100 new customers, assuming each conversion represents one customer and the measurement period is consistent.
If the average first purchase is $30, projected revenue from those new customers would be:
\[ 100\times \$30=\$3,000 \]
These figures are illustrative, not industry benchmarks or predictions. A real business should use observed conversion data whenever available.
Accounting for Recurring Revenue and Customer Retention
Recurring revenue models require particular attention to customer retention. A company may acquire many new subscribers but still struggle if existing customers cancel at a high rate.
The financial model should distinguish between new customers, retained customers, and lost customers. It should also consider whether customers upgrade, downgrade, or purchase additional services.
Retention influences more than revenue. It affects the amount the startup must spend replacing lost customers and the resources required to maintain a stable customer base.
For this reason, business growth projections should not rely entirely on increasing new customer acquisition. They should also consider how effectively the company maintains its existing relationships.
Avoiding Unrealistic Revenue Expectations
A useful forecast is based on assumptions that can be explained and tested. Founders should consider the time required to launch, the speed at which customers discover the offering, the purchasing process, competition, seasonal changes, and the company’s ability to deliver what it sells.
It is generally more useful to build a realistic monthly forecast than to apply an aggressive annual growth percentage without explaining how that growth will occur.
As actual sales information becomes available, assumptions should be updated. Financial modeling becomes more reliable when projections gradually reflect real business experience rather than remaining tied to the founder’s original expectations.
Estimating Operating Costs and Initial Expenses
Revenue tells only part of the financial story. A startup also needs to understand how much money it must spend to create, deliver, market, and support its products or services.
Expense forecasting helps founders determine whether their pricing structure is sustainable and how much capital they need to begin operations. Underestimating expenses can create problems even when the business attracts customers.
Fixed Costs
Fixed costs are expenses that generally remain stable within a relevant operating range and time period. They may include:
- Office or workspace rent.
- Regular employee salaries.
- Software subscriptions.
- Insurance payments.
- Accounting and professional fees.
- Certain administrative expenses.
Fixed costs are important because they create financial obligations that may continue even when sales decline.
A startup with significant fixed expenses may need a larger cash reserve than a business that can adjust its costs more easily.
Variable Costs
Variable costs change with production, sales, or service activity. Examples include raw materials, product packaging, delivery expenses, transaction fees, and certain production-related labor costs.
For a physical product business, selling more units may increase manufacturing and shipping costs. For a digital subscription company, transaction fees or usage-based infrastructure expenses may rise as the number of customers increases.
Understanding variable costs helps founders calculate gross profit and determine whether additional sales improve the company’s financial position.
Payroll and Hiring Expenses
Employees can represent one of the largest financial commitments for an early-stage startup. A financial model should include more than basic salaries when estimating the cost of hiring.
Depending on the location and employment arrangement, the business may also need to budget for payroll taxes, benefits, recruitment, training, equipment, and other employment-related costs.
Founders should also forecast hiring dates rather than assuming that every employee will be needed from the first month. Staggering recruitment according to business requirements may help preserve cash during the early stages.
Marketing and Customer Acquisition Expenses
Marketing expenses can include paid advertising, content production, design, promotional campaigns, sales commissions, public relations, and marketing software.
A useful model connects marketing spending with customer acquisition assumptions. If a startup spends more money on advertising, it should examine whether the expected increase in customers justifies the additional cost.
The relationship between acquisition spending and customer value is important. Spending more to acquire customers does not necessarily improve the business if those customers generate insufficient revenue or leave quickly.
Technology and Infrastructure
Technology expenses vary depending on the type of startup. A software company may need cloud hosting, development tools, security services, testing environments, and technical support. An online retailer may require an e-commerce platform, payment processing, inventory management, and website maintenance.
These costs should be classified according to how they are incurred. Some are fixed monthly subscriptions, while others depend on usage or transaction volume.
Founders should also consider future capacity. A service that is inexpensive during early testing may become more expensive when usage increases.
Unexpected and Overlooked Expenses
Even a detailed budget cannot predict every cost. Equipment may need replacement, suppliers may change prices, customers may request refunds, and product development may take longer than expected.
A financial model should include a reasonable contingency allowance based on the startup’s risk profile. This does not mean adding an arbitrary amount to every expense. It means acknowledging that estimates involve uncertainty and that businesses need some flexibility.
The objective is to avoid treating the initial budget as a perfect prediction of future spending.
Understanding Cash Flow During the Early Business Stages
Cash flow forecasting is essential because a startup can appear profitable on paper while experiencing a shortage of money in its bank account.
Revenue and cash are related, but they are not identical. Revenue generally represents income earned through business activities, while cash flow measures the actual movement of money into and out of the company.
This difference can create serious difficulties for startups that sell on credit, rely on delayed customer payments, or must pay suppliers before receiving money from buyers.
Why Revenue Does Not Always Mean Available Cash
Imagine a hypothetical startup completes a $10,000 project in March but agrees to receive payment in May. The company may recognize the revenue in March under the applicable accounting rules, depending on the contract and accounting treatment.
However, the money is not available in March.
If the business needs to pay employees, software providers, and suppliers during April, it must have sufficient cash to meet those obligations.
This example demonstrates why financial planning should include both revenue forecasting and cash flow forecasting. A company needs to understand not only how much it expects to earn but also when payments are likely to arrive.
The Main Components of Cash Flow
A startup’s cash flow model generally considers three categories:
Operating cash flow: Money generated or used through normal business operations, including customer receipts, supplier payments, salaries, and operating expenses.
Investing cash flow: Money spent on or received from longer-term assets and investments, such as equipment or certain business acquisitions.
Financing cash flow: Money received from investors, lenders, or other financing activities, as well as repayments and certain distributions.
These categories help founders understand where cash comes from and where it goes. The distinction is important because receiving investment money does not mean the underlying business operations are profitable.
Managing Payment Delays
Payment delays can create cash shortages even when a startup has a healthy sales pipeline. Businesses that provide services to other companies may wait for invoices to be approved and paid.
Founders can manage this risk by establishing clear payment terms, monitoring outstanding invoices, requesting deposits where appropriate, and following up on overdue payments.
They should also consider the timing of supplier obligations. Negotiating payment schedules that better match customer receipts can reduce pressure on working capital.
Working Capital and Liquidity
Working capital broadly describes the difference between current assets and current liabilities. It provides a way to examine whether a business has sufficient short-term resources to meet its near-term obligations.
A startup may have valuable equipment, a promising product, and substantial future sales potential, but still experience a liquidity problem if it cannot pay immediate bills.
Cash reserves and working capital planning are therefore central to sustainable operations. The purpose of a cash flow forecast is to identify potential shortages early enough for the founder to consider appropriate responses.
Burn Rate: Measuring Monthly Cash Consumption
Burn rate describes how quickly a startup uses cash to support its operations, particularly when its operating activities consume more cash than they generate.
Two common measures are:
- Gross burn rate: Total cash operating expenses during a period.
- Net burn rate: The amount by which cash outflows exceed cash inflows during a period.
Consider a hypothetical startup that spends $18,000 in a month and receives $7,000 in operating cash inflows. Its simplified net burn rate is:
\[ \$18,000-\$7,000=\$11,000 \]
The business is using $11,000 of net cash during that month.
The calculation is simplified and should be adapted to the company’s actual cash flow statement. Financing receipts, capital expenditure, unusual payments, and changes in working capital may also affect cash balances.
Runway: Estimating How Long Cash Will Last
Runway estimates how long a startup can continue operating before its available cash is exhausted, assuming a particular pattern of cash consumption.
A simplified calculation is:
\[ \text{Runway}=\frac{\text{Available Cash}}{\text{Monthly Net Burn Rate}} \]
If a hypothetical startup has $66,000 in available cash and a monthly net burn rate of $11,000, its estimated runway is:
\[ \$66,000\div \$11,000=6\text{ months} \]
This is a simplified illustration, not a guarantee that the business will have exactly six months to operate. Actual burn rates can change, and the company may need to maintain a minimum cash reserve.
Runway calculations help founders understand when they may need to reduce expenses, improve collections, generate more revenue, or explore additional financing.
How Founders Calculate Startup Funding Requirements
A startup’s funding requirement is the amount of capital it needs to launch, operate, and reach its next meaningful business milestone. The amount depends on the business model, the timing of expenses, the pace of revenue generation, and the cash reserve required to manage uncertainty.
Financial modeling helps founders estimate this requirement instead of selecting a funding target without a clear explanation. It can also show whether the business can begin with a smaller initial investment or whether its operational requirements make additional capital necessary.
Calculating the Initial Capital Requirement
A practical funding estimate starts by identifying the costs that must be covered before the business becomes financially self-supporting. These may include product development, equipment, initial inventory, licensing, marketing, and the expenses associated with the first months of operation.
The calculation should also account for expected cash receipts and any existing capital the founder can contribute.
A simplified framework is:
\[ \begin{aligned} \text{Funding Requirement}={}&\text{Initial Costs}\\ &+\text{Projected Cash Shortfall}\\ &+\text{Cash Reserve}\\ &-\text{Available Capital} \end{aligned} \]
This is a planning framework rather than a complete accounting formula. A detailed model should calculate the monthly cash position and identify the highest cumulative funding deficit, while avoiding double-counting initial costs already included in projected cash outflows.
A Hypothetical Funding Example
Suppose a startup expects to spend $12,000 preparing its product for launch. It forecasts an additional cumulative operating cash shortfall of $30,000 before operations stabilize and wants to retain a $10,000 cash reserve.
If the founder has already committed $7,000 of personal capital, a simplified funding estimate would be:
| Component | Hypothetical amount |
|---|---|
| Initial setup costs | $12,000 |
| Expected operating cash shortfall | $30,000 |
| Desired cash reserve | $10,000 |
| Total planned requirement | $52,000 |
| Founder capital available | $7,000 |
| Additional funding indicated | $45,000 |
These figures are illustrative, not a real company’s financial results. The actual requirement would depend on the monthly timing of expenses, customer receipts, taxes, financing costs, and other relevant items.
The example demonstrates why funding requirements should be connected to an operating plan. A founder should be able to explain what the money will cover, how long it is expected to last, and which milestones it should help the business achieve.
Choosing Between Bootstrapping and External Funding
Bootstrapping allows founders to finance operations through personal resources, early revenue, and other internally available funds. It can reduce reliance on outside investors, but it also limits the amount of capital available for expansion.
External funding may provide additional resources for product development, recruitment, marketing, or market entry. However, equity investment can dilute ownership, while debt financing introduces repayment obligations and potentially interest costs.
The appropriate approach depends on the business’s capital requirements, growth opportunities, risk tolerance, and ability to generate cash. A financial model helps founders compare these options by examining their likely effects on cash flow, ownership, obligations, and growth.
Entrepreneurs exploring different business models can also benefit from broader discussions of entrepreneurship and startup funding, while keeping in mind that any particular funding decision requires analysis of the company’s own circumstances.
Preparing for Investor Discussions
A financial model should explain the logic behind the requested investment. Founders should be able to show how the funds will be allocated, what the business expects to achieve, and what could happen if revenue grows more slowly than expected.
Investors may examine assumptions about customer acquisition, gross margins, staffing, cash consumption, and the timing of future financing. They may also question whether the company’s projected growth is supported by evidence.
The model does not need to predict every outcome accurately. It needs to be internally consistent, transparent about uncertainty, and useful for understanding the business’s financial needs.
Financial Modeling and Break-Even Analysis
Break-even analysis estimates the level of sales at which a business’s revenue covers its costs. At this point, the company neither makes an operating profit nor incurs an operating loss under the assumptions used in the calculation.
For a startup, break-even analysis can answer an important question: how much does the business need to sell before its operations cover their costs?
Understanding Contribution Margin
The contribution margin is the amount remaining from each sale after subtracting the variable costs directly associated with that sale.
For a simplified product business:
\[ \text{Contribution per Unit}=\text{Selling Price}-\text{Variable Cost per Unit} \]
If a hypothetical startup sells a product for $50 and incurs $20 in variable costs per unit, its contribution per unit is $30.
That $30 contributes toward fixed costs. Once those costs have been covered, additional contribution can support operating profit, assuming other relevant costs and conditions remain unchanged.
Calculating the Break-Even Point
For a business selling a single product or a consistent mix of products, the simplified break-even formula is:
\[ \text{Break-Even Units}= \frac{\text{Fixed Costs}}{\text{Contribution per Unit}} \]
Suppose a hypothetical startup has monthly fixed costs of $6,000 and earns a contribution of $30 per unit.
\[ \$6,000\div \$30=200\text{ units} \]
Under these assumptions, the startup must sell 200 units per month to cover its fixed costs. This is a simplified operating calculation; the actual break-even point may differ if the business has multiple products, additional expenses, financing costs, or changing unit economics.
Why Break-Even Analysis Matters
Break-even analysis helps founders evaluate pricing, cost control, and sales targets. If the required sales volume appears unrealistic, the business may need to change its pricing, reduce expenses, improve its contribution margin, or reconsider its operating model.
It can also help entrepreneurs compare alternatives. For example, a more expensive product might generate a higher contribution per sale but attract fewer customers. A lower price could increase sales volume while reducing the margin earned on each transaction.
The financial model allows founders to explore these relationships instead of evaluating each decision in isolation.
Accounting Break-Even Versus Cash Break-Even
Accounting break-even and cash break-even are related but different concepts. Accounting break-even focuses on whether recognized revenue covers the relevant expenses under the chosen accounting treatment. Cash break-even focuses on whether cash receipts cover cash payments over a defined period.
A company may reach accounting break-even while still experiencing cash pressure because customers pay late, inventory must be purchased in advance, or loan principal repayments consume cash.
Founders should therefore use break-even analysis alongside cash flow forecasting rather than treating it as a complete measure of financial health.
Scenario Planning: Preparing for Different Business Outcomes
A financial model should not rely on one forecast as if the future were certain. Startups operate in changing markets, and small differences in customer behavior or operating costs can produce meaningful financial consequences.
Scenario planning helps founders explore several plausible outcomes and identify which assumptions have the greatest effect on the business.
The Conservative Scenario
A conservative scenario examines what might happen if important business conditions develop less favorably than expected. Sales may grow slowly, customer acquisition may cost more, payments may arrive late, or suppliers may charge higher prices.
The purpose is not to predict failure. It is to determine whether the business has enough flexibility to respond if conditions become difficult.
A conservative forecast may reveal that the startup needs more cash than originally planned or should delay hiring until revenue becomes more reliable.
The Expected Scenario
The expected scenario represents the founder’s most reasonable working forecast based on currently available information. It should not simply be the midpoint between the optimistic and conservative cases.
Instead, its assumptions should reflect the best available understanding of customer demand, pricing, operating costs, and the time required to execute the business plan.
As the startup gathers actual results, this scenario should be updated to reflect what is happening rather than preserving outdated expectations.
The Optimistic Scenario
An optimistic scenario explores what might happen if favorable conditions develop. The business may acquire customers more efficiently, retain subscribers for longer, increase average order values, or negotiate better supplier terms.
This scenario can help founders identify opportunities for growth and understand the resources required to support them.
However, it should not be used as the only basis for spending commitments. A company that hires aggressively or signs expensive contracts based solely on its most favorable forecast may expose itself to unnecessary financial risk.
Comparing Scenarios With Illustrative Numbers
Consider a hypothetical startup with monthly fixed costs of $6,000 and a contribution margin of 60%. For simplicity, assume that contribution margin remains constant across the scenarios and that the figures exclude financing costs, taxes, and other adjustments.
| Scenario | Monthly revenue | Contribution at 60% | Less fixed costs | Simplified operating result |
|---|---|---|---|---|
| Conservative | $8,000 | $4,800 | $6,000 | -$1,200 |
| Expected | $12,000 | $7,200 | $6,000 | $1,200 |
| Optimistic | $16,000 | $9,600 | $6,000 | $3,600 |
These are hypothetical figures intended to illustrate the calculation, not predictions about an actual startup.
The comparison shows how the same cost structure can produce a loss, a modest surplus, or a stronger operating result depending on revenue. It also reveals that revenue alone does not explain the outcome; the contribution margin and fixed expenses are equally important.
Sensitivity Analysis: Testing Individual Assumptions
Scenario planning considers combinations of changes, while sensitivity analysis examines how changing one or more inputs affects a specific result.
A founder might test what happens if customer acquisition costs rise by 20%, the selling price falls by 10%, or customer cancellations increase. The model can show how each change affects revenue, profitability, and cash requirements.
This is useful because it identifies the assumptions that deserve the closest monitoring. If a small change in customer retention has a large impact on runway, the business may need to prioritize retention rather than concentrating exclusively on acquiring new customers.
Financial Modeling Mistakes That Can Mislead Entrepreneurs
A financial model is only as useful as its assumptions, structure, and interpretation. A spreadsheet can produce precise-looking numbers even when its underlying assumptions are unrealistic.
Founders should therefore pay attention to the quality of the reasoning behind the model rather than assuming that detailed calculations automatically produce reliable forecasts.
Overestimating Sales Growth
One common mistake is projecting rapid sales growth without explaining how the company will attract and retain customers.
An ambitious target can be useful as a goal, but it should not be confused with a realistic financial forecast. Sales assumptions should reflect pricing, distribution, customer acquisition, conversion rates, competition, and operational capacity.
Where evidence is limited, founders should make uncertainty visible and test alternative outcomes.
Underestimating Operating Expenses
Startups may focus heavily on product development while overlooking recruitment, customer support, payment fees, maintenance, taxes, and administrative costs.
Some costs also increase as the business grows. A company may need more support staff, additional infrastructure, or higher inventory levels to serve a larger customer base.
Expense forecasts should reflect the way operations are expected to develop rather than assuming that costs remain constant regardless of growth.
Confusing Revenue With Profit
Revenue is the income generated through sales and other business activities. Profit is what remains after the relevant expenses are deducted.
A startup can generate substantial revenue and still lose money if its direct costs, payroll, marketing, and other expenses are too high.
Founders should examine gross profit, operating profit, and net profit as appropriate, while recognizing that each measure answers a different question.
Ignoring Cash Timing
A forecast may show that the business expects to earn more than it spends over a quarter, yet it may still run out of cash during one of the months.
This can happen when customers pay late or the company must make large payments before receiving sales revenue. Monthly cash flow projections are particularly important when working capital is limited.
Treating All Costs as Fixed
Some models assume that operating expenses remain unchanged even when production or customer numbers increase. This can produce misleading profitability forecasts.
Variable costs, usage-based technology expenses, shipping, transaction fees, and certain labor costs may rise with business activity. The model should reflect these relationships wherever they materially affect results.
Building an Overly Complicated Spreadsheet
Complexity is not the same as accuracy. A model with excessive formulas, unclear tabs, and undocumented assumptions can become difficult to maintain.
Founders should begin with the calculations necessary to understand the business and add detail when it improves decisions. Every important output should be traceable to its underlying assumptions.
Failing to Update the Forecast
A financial model created before launch can become outdated quickly as real data becomes available. If actual customer demand, pricing, costs, or payment patterns differ from the original plan, the model should be revised.
Regular updates help founders recognize changes early and make adjustments based on current information rather than outdated expectations.
Choosing the Right Tools for Startup Financial Planning
Financial modeling does not require an expensive software platform from the beginning. Many entrepreneurs can develop a useful first model with a spreadsheet and a clear understanding of their business’s revenue drivers, costs, and cash requirements.
The right tool depends on the startup’s size, complexity, reporting needs, and available resources. A simple service business may need only a modest monthly forecast, while a company with multiple products, international operations, inventory, and outside investors may need a more structured system.
Spreadsheet-Based Financial Modeling
Spreadsheet applications are a practical starting point because they allow founders to organize assumptions, perform calculations, and compare scenarios in one place.
A basic startup financial model can use separate worksheets for assumptions, revenue, expenses, cash flow, profit and loss, and scenario analysis. Formulas connect these sections so that changing a key input updates the relevant calculations.
For example, changing the subscription price should update projected revenue, while changing the number of employees should affect payroll expenses and the cash forecast.
Spreadsheets also make it relatively easy to share assumptions with business partners or advisers. However, formulas should be documented, inputs should be separated from calculations, and important outputs should be checked to reduce the risk of errors.
Dedicated Financial Modeling Software
Specialized financial modeling tools can be useful when a business needs collaborative planning, integrated financial reporting, multiple operating scenarios, or connections to accounting systems.
Depending on the product, these tools may offer templates, forecasting workflows, permissions, reporting dashboards, and automated data imports. Their capabilities vary, so founders should compare actual functionality rather than assume that every tool provides the same features.
Before purchasing a subscription, entrepreneurs should consider whether the software solves a genuine problem. A complicated platform may add unnecessary expense if the business only needs a basic forecast.
Accounting Software and Financial Models Serve Different Purposes
Accounting software primarily helps record and organize financial transactions. Financial modeling estimates possible future outcomes based on assumptions about what may happen.
The two can work together. Actual accounting data provides a reference point for evaluating the forecast, while the model helps the founder consider future hiring, investment, and operating decisions.
However, historical accounting records do not automatically create an accurate forecast. The founder must still make assumptions about future revenue, expenses, payment timing, and business activity.
For readers exploring the relationship between business processes and digital tools, OurMagazine.blog’s discussion of business and technology topics offers broader context on how online information can help introduce commercial concepts. Financial decisions should still be based on the startup’s own records and appropriate professional guidance.
What a Useful Financial Model Should Include
Regardless of the tool selected, a practical model should make it easy to identify the key assumptions, understand the calculations, and compare projected results with actual performance.
At a minimum, the founder should be able to determine how much revenue the business expects, which costs have the greatest impact, when cash may become insufficient, and how much additional funding might be required.
The model should also be easy to update. If making a simple pricing change requires rebuilding the entire spreadsheet, the structure may be unnecessarily complicated.
How Financial Models Change as a Business Grows
The financial requirements of a startup change as it moves from an initial idea toward a functioning business. Early models may rely heavily on estimates, while later models can incorporate customer data, historical expenses, and observed operating patterns.
Financial modeling should develop alongside the company rather than remain frozen at the level of its original business plan.
The Idea and Validation Stage
At the idea stage, founders may have limited information about customer demand, pricing, or the cost of delivering the product. The financial model should therefore focus on basic feasibility.
The founder can estimate initial costs, test different pricing structures, and calculate how many customers might be required to support the business.
The purpose is to identify major financial risks before committing substantial resources. It is not to produce a detailed five-year forecast that gives uncertain assumptions a false appearance of precision.
The Launch Stage
Once the business begins operating, founders can replace some assumptions with actual observations. They may learn how long customers take to make purchasing decisions, which marketing channels produce sales, and which operating costs were underestimated.
The model should incorporate these findings. If product development takes longer than expected, the forecast may need to account for additional expenses and delayed revenue.
At this stage, cash flow forecasting becomes especially important because the business is learning how its actual payment patterns compare with the original plan.
The Early Growth Stage
As revenue becomes more established, the company may consider hiring employees, entering new markets, expanding its product range, or investing more heavily in marketing.
Each decision creates financial consequences that should be examined before implementation. Additional sales may require more inventory, larger infrastructure capacity, or more customer support.
A growing startup should therefore connect its growth plans with operating capacity and cash requirements. Revenue growth is valuable only when the business can support the additional activity and manage its associated costs.
The Scaling Stage
At a more advanced stage, financial modeling may include department-level budgets, hiring plans, detailed customer retention forecasts, capital expenditure, and more formal reporting.
Founders may also need to compare different funding options and examine how financing decisions affect ownership, repayment obligations, and future cash flow.
A more sophisticated model can support these decisions, but it should still remain understandable. Complexity should reflect the company’s actual needs, not the desire to create an impressive-looking financial document.
Using Actual Results to Improve Forecasts
One of the most valuable habits in startup financial planning is comparing the forecast with actual performance.
If sales are lower than projected, the founder should investigate the reason rather than simply reducing the next forecast. If expenses are higher, the model should identify which costs changed and whether the increase is temporary or recurring.
These comparisons help the business improve its assumptions over time. They also encourage founders to treat financial planning as a management process rather than an administrative task completed only when seeking funding.
Practical Applications of Financial Modeling for Founders
The usefulness of startup financial modeling becomes clearer when it is connected to everyday business decisions. A model can help entrepreneurs evaluate the financial consequences of changing prices, hiring employees, launching products, and expanding operations.
Evaluating a Pricing Decision
Suppose a hypothetical startup is considering reducing its product price to attract more customers. The founder can model the effect of the lower price on contribution margin and calculate how many additional sales would be required to compensate for the reduction.
If the business must sell substantially more units to maintain the same contribution, the founder needs to determine whether demand is likely to increase enough to justify the change.
This is more useful than assuming that lower prices automatically lead to higher profits.
Deciding When to Hire
Hiring can increase the company’s ability to deliver products, support customers, or develop new features. It also creates recurring financial commitments.
A founder can model the proposed employee’s total cost, the expected start date, and the revenue or operational benefits the role is intended to support.
The model may reveal that hiring immediately would reduce runway too sharply, while delaying recruitment could create capacity problems. The decision should balance financial flexibility with the company’s actual operational needs.
Comparing Marketing Strategies
A startup may need to choose between several marketing channels, each with different costs and expected outcomes.
Financial modeling can compare the expected acquisition cost, conversion rate, customer value, and payback period associated with each option. Because these inputs are uncertain, the founder should test a range of plausible outcomes rather than relying on one estimate.
The goal is to understand which strategy appears financially attractive under reasonable assumptions and what evidence is needed to validate those assumptions.
Planning a Product Launch
Launching a new product may require development spending, inventory purchases, packaging, promotion, and customer support before sales become consistent.
A financial model can estimate the timing of these expenses and compare them with expected sales receipts. It can also examine how delays affect the cash balance.
This allows the founder to identify whether the launch requires additional capital, a smaller initial release, or a different spending schedule.
Making Expansion Decisions
Expansion may involve entering a new geographic market, opening a location, adding a service, or increasing production capacity. These decisions can increase revenue potential but also introduce new costs and risks.
A model helps founders compare the investment required with the expected financial outcome. It can also test what happens if the new market grows more slowly than anticipated.
For broader context on entrepreneurship and business development, the business-focused material available on OurMagazine.blog provides an additional starting point for exploring related commercial subjects.
Frequently Asked Questions About Startup Booted Financial Modeling
1. What does Startup Booted Financial Modeling mean?
Startup Booted Financial Modeling refers here to the process of creating financial forecasts for an early-stage business, particularly one managing limited resources or considering a bootstrapped launch. It connects business assumptions with projected revenue, expenses, cash flow, funding needs, and profitability. The phrase is used as an educational concept, not as the verified name of a specific company or software product.
2. Why do startups need financial models?
Startups use financial models to understand the financial consequences of business decisions before making substantial commitments. A model can help founders estimate launch costs, identify future cash shortages, evaluate pricing, plan recruitment, and determine how much capital may be required. It also provides a reference point for comparing actual results with expectations.
3. What are the main components of a startup financial model?
A typical model includes revenue projections, operating expenses, startup costs, cash flow forecasts, a projected profit and loss statement, and relevant balance sheet information. It should also document important assumptions and may include break-even analysis, burn rate, runway, and scenario planning. The level of detail depends on the business model and the decisions the founder needs to make.
4. How do founders estimate startup revenue?
Founders estimate revenue by identifying the business’s main sales drivers. These may include product prices, units sold, customer conversion rates, subscription numbers, customer retention, and average transaction values. Early estimates should be treated as assumptions and updated as actual sales information becomes available. Revenue projections are more useful when their underlying calculations can be explained and tested.
5. What is the difference between cash flow and profit?
Profit measures the difference between recognized revenue and the relevant expenses under the applicable accounting treatment. Cash flow measures money entering and leaving the business. A company may report a profit while experiencing a cash shortage because customers have not paid their invoices, inventory purchases require advance payment, or other cash obligations fall due. Both measures are necessary for understanding financial performance.
6. How do burn rate and runway affect financial planning?
Burn rate indicates how quickly a startup consumes cash, while runway estimates how long its available cash may last at a particular rate of consumption. These measures help founders understand when they may need to reduce expenses, increase revenue, obtain financing, or adjust their operating plans. Because cash consumption changes over time, runway should be recalculated as the company’s financial position develops.
7. Which tools can entrepreneurs use for financial modeling?
Entrepreneurs can begin with spreadsheet applications that organize assumptions, formulas, revenue forecasts, expenses, and cash flow projections. As the business grows, dedicated planning software or accounting integrations may become useful. The best choice depends on the complexity of the company, the need for collaboration, the quality of available financial data, and the cost of maintaining the system.
8. How frequently should a startup update its financial model?
A startup should update its model regularly and whenever a significant change affects its assumptions. Many early-stage businesses benefit from reviewing actual results against the forecast each month, although cash-sensitive businesses may need more frequent monitoring. Important triggers include a major customer contract, a hiring decision, an unexpected expense, a change in pricing, or a significant shift in sales.
9. Can a financial model help a startup prepare for investors?
Yes. A well-structured model can help founders explain their funding requirements, expected use of capital, revenue assumptions, operating costs, and potential growth. It also allows investors to examine how changes in key assumptions may affect the business. However, a financial model cannot guarantee investment or prove that a startup will achieve its projections. Its value depends on the quality of its assumptions, consistency, and transparency.
Conclusion: Financial Modeling as an Ongoing Business Discipline
Startup Booted Financial Modeling is best understood as a practical way to connect entrepreneurial ambition with financial reality. It helps founders move beyond broad expectations and examine the numbers that determine whether a business can launch, operate, and grow sustainably.
A useful model brings together revenue projections, operating expenses, cash flow, funding requirements, and profitability analysis. These elements cannot be considered independently. Higher sales may increase revenue, but they can also require additional inventory, employees, infrastructure, and marketing expenditure. A business may report a profit while facing a cash shortage, and a company with promising growth prospects may still require more capital than its founders initially expected.
Financial modeling helps make these relationships visible. It gives entrepreneurs a structured way to evaluate pricing, hiring, product launches, marketing decisions, and expansion plans. It can also help them prepare for difficult conditions by testing how lower sales, higher costs, or delayed payments affect their financial position.
The most useful financial model is not necessarily the most complicated one. It is the model that reflects the business’s actual operating structure, documents its assumptions, and makes important financial relationships easy to understand. Early estimates should be treated as provisional, and projections should become more evidence-based as real operating data becomes available.
Founders should also remember that financial forecasts are not guarantees. Market demand can change, customers can behave differently than expected, and unforeseen expenses can affect the business. A well-prepared model acknowledges these uncertainties instead of hiding them behind precise-looking figures.
Ultimately, startup financial planning should be treated as a recurring management discipline rather than a spreadsheet exercise completed before launch. By reviewing actual results, updating assumptions, monitoring cash reserves, and testing important decisions before committing resources, entrepreneurs can make better-informed choices throughout the life of their businesses. The real value of financial modeling lies not in predicting every outcome correctly, but in helping founders recognize what their decisions may cost, what their business needs to succeed, and when their original plan needs to change.
For More Visits: Ourmagazine

Leave a Comment
Your email address will not be published. Required fields are marked with *